
78% of fixed-rate securitized CRE debt maturing through 2028 carries an interest rate well below the current 10-year Treasury yield, a total of $179 billion in exposed debt.
the risk of loans maturing into higher rates has been widely discussed since 2023, but two things are different now. The market largely expects rates to stay elevated, and lenders are moving away from the extend-and-pretend approach that has dominated the past four years.
Stress is most visible in CMBS. The overall CMBS delinquency rate reached 7.85% in August, and non-performing matured loans accounted for 81% of newly delinquent balances.
Higher financing costs and lower valuations are narrowing the options to extend or refinance, so more distress is being resolved through transactions. Over the past 12 months, more than 40% of properties across asset classes traded below their inflation-adjusted prior sale prices. The result is a market gradually moving from extending troubled loans to recognizing losses and resetting values to today’s cost of capital.
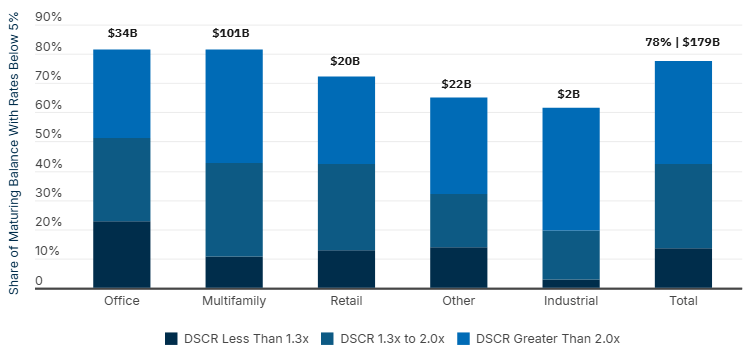
Source: Newmark

